the Future of Hospitality
← NieuwsARTIKEL
Insights

Herpositioneren met de exit in gedachten: wat de case van het Grand Hotel Central Barcelona asset managers leert

the Future of Hospitality · 3 sep 2026 · 18 MIN LEZEN
Herpositioneren met de exit in gedachten: wat de case van het Grand Hotel Central Barcelona asset managers leert

Herpositioneren met de exit in gedachten is zo'n zin die in de bestuurskamer vanzelfsprekend klinkt en rond maand zes van elk hotelproject vergeten is. De case van het Grand Hotel Central Barcelona, tussen eind 2021 en begin 2026 gedraaid door het team van Schroders Capital, laat zien wat er gebeurt als een team weigert die zin te vergeten. De RGI ging van 64 naar 108. Het hotel staat al in de verkoop. En het plan voor de volgende eigenaar stond vanaf dag één in de strategie.

Een goede asset manager leest de cijfers. Een uitstekende leest wat erachter zit.

Het gat tussen een vakbekwame asset manager en een uitstekende is kleiner dan de meeste eigenaren denken, en groter dan de meeste cv's doen vermoeden. Een vakbekwame asset manager kan een P&L lezen, een budget uitdagen en RevPAR, GOP en cashflow bewaken. Dat is de technische basis. Zonder die basis doe je niet mee.

Het probleem is dat cijfers altijd te laat komen. Tegen de tijd dat een zwakke maand in de managementrapportage opduikt, is de prijsdiscipline weken eerder al verslapt, was de general manager zijn tijd al kwijt aan het verkeerde gevecht, en heeft de CapEx-post die waarde moest toevoegen stilletjes het product verbeterd zonder de waarde van het asset te verhogen.

Dat is de laag van het oordeel. Dat is wat rapporteren onderscheidt van beslissen.

Een vakbekwame asset manager stuurt de eigenaar een variantierapport. Een uitstekende vertaalt dat rapport naar een besluit: wat verandert er, wie beslist, wanneer, en wat gebeurt er als we niets doen. De rapportage is in beide gevallen dezelfde. Wat de investeerder eraan heeft, verschilt volledig.

Er is een tweede gat dat onder druk zichtbaar wordt. Hotels zijn operationele bedrijven, gerund door exploitanten die geven om gasten, servicestandaarden en personeel, en gefinancierd door investeerders die geven om IRR, houdperiodes en exitmultiples. Beide groepen hebben gelijk. Beide groepen stoppen vaak met luisteren na de tweede zin.

De asset manager zit daartussen. Spreek je maar één van die twee talen vloeiend, dan word je door de andere kant getolereerd maar nooit vertrouwd. Spreek je ze allebei, dan word je degene die gebeld wordt vóór het besluit, niet erna. Daar wordt de waarde gemaakt.

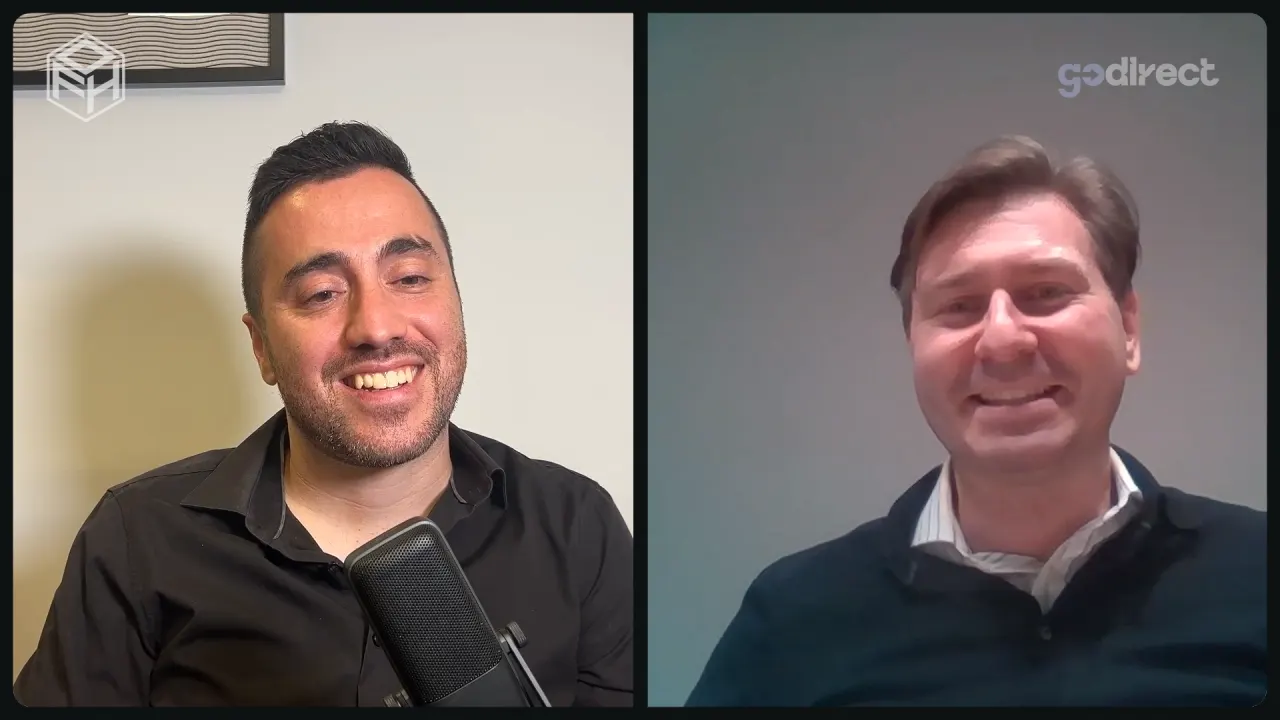
Wie er achter de Barcelona-case zit: Emmanuel Disset en Dario Filipponi van Schroders Capital

Het Grand Hotel Central Barcelona zit in de hotelportefeuille van Schroders, en die portefeuille is niet klein. Emmanuel Disset is Head of Asset Management voor Schroders Hotels. Hij beheert 45 hotels in 9 landen, samen ongeveer 3,6 miljard euro waard.

Die schaal is bepalend voor de manier waarop de Barcelona-case is aangepakt. Als je 45 assets beheert, kun je je niet veroorloven om voor elk asset een nieuw draaiboek te verzinnen. Je hebt een herhaalbare manier van denken nodig over waardecreatie, tijdlijnen en exit, en je hebt mensen nodig die dat lokaal kunnen toepassen zonder op het hoofdkantoor te wachten voor elk besluit.

Dario Filipponi is een van de asset managers in dat team. Hij is verantwoordelijk voor 6 assets tussen Polen en Spanje, wat neerkomt op veel vliegvelden en werkkennis van twee heel verschillende regelgevende en operationele omgevingen. Hij trekt het Grand Hotel Central sinds 2021, de volledige lengte van de houdperiode.

Bij die continuïteit is het de moeite waard om stil te staan. Een houdperiode van vijf jaar met dezelfde asset manager van aankoop tot verkoop is niet de norm in de branche. In veel fondsen is degene die het asset koopt niet degene die het verkoopt, en lekt er stilletjes kennis uit het dossier telkens als iemand nieuw het oppakt.

Hier is degene die het oorspronkelijke businessplan tekende ook degene die de verkoopprijs verdedigt. Dat is geen zacht voordeel. Het is precies wat het team in staat stelde om de exit vanaf dag één in gedachten te houden, omdat het hoofd dat de exit vasthield halverwege niet veranderde.

Emmanuel en Dario werkten al lang vóór Barcelona samen, en dat is de andere reden dat de interne besluitvorming kort bleef. Toen de lokale exploitant hen verraste, of toen de F&B-relaunch binnen dagen in plaats van weken een besluit nodig had, hoefden ze geen vertrouwen meer op te bouwen.

Er is geen rechte lijn naar hotel asset management, en dat is nu juist het punt

Niemand begint een loopbaan met de wens hotel asset manager te worden. Emmanuel begon in de operatie, als analist bij het Intercontinental in Berlijn in het begin van de jaren negentig. Daarna stapte hij over naar finance, als accountant bij wat toen het Churchill Intercontinental in Londen was en nu een Hyatt is.

Die combinatie, operatie aan de ene kant en financiële discipline aan de andere, is de basis die hij nog steeds het nuttigste deel van zijn cv noemt. Zijn eerste echte asset-managementrol kwam bij IHG in het Verenigd Koninkrijk, en daarna werkte hij voor eigenaren van Hilton-hotels. Stap voor stap leerde hij hoe hotels op de vloer echt werken, en wat eigenaren werkelijk van een portefeuille willen.

De route van Dario ziet er anders uit en eindigt op dezelfde plek. Na eerste operationele ervaring stapte hij over naar strategisch advies, vlak na de financiële crisis van 2008. Hij zat in Afrika en adviseerde eigenaren op het hele continent die nieuwe hotels openden of, vaker nog, probeerden te redden wat ze al hadden vastgelegd.

Asset-managementopdrachten kwamen binnen omdat eigenaren na de crisis hun strategie moesten herschikken en die snel moesten uitvoeren. Hij deed het asset management van een hotel op Mauritius, daarna van een hotel in Kaapstad, en bouwde geleidelijk het scala aan situaties op dat je alleen leert door het mee te maken.

De les voor wie wil aannemen, of wie wil instappen, is dat operatie, finance, ontwikkeling, advies en revenue management allemaal naar dezelfde deur leiden. Wat telt is of je de hotelrealiteit kunt verbinden met de financiële doelen van de eigenaar zonder een van beide kanten kwijt te raken.

Het Grand Hotel Central Barcelona: 146 kamers, 8 miljoen euro CapEx en een bewuste keuze voor eigen exploitatie

Het asset zelf is een hotel met 146 kamers in de gotische wijk van Barcelona, met drie food-and-beverage-outlets. Schroders kocht het eind 2021. Ze besteedden ruim 8 miljoen euro aan een volledige renovatie en herpositionering.

De structurele beslissing die al het andere bepaalde was de overstap van een klassiek hotelmanagementcontract naar eigen exploitatie. Dat is geen cosmetische wissel. Het verandert wie de prijzen, het aannamebeleid, de merkstem en de F&B-strategie bepaalt, en het verandert wat een toekomstige koper erft.

De cijfers vertellen het verhaal compact. De RGI ging van 64 in 2022 naar 108 in 2026. Voor wie buiten het vak staat: de Revenue Generation Index zet de kameromzet van een hotel af tegen die van zijn concurrentieset. Van 64 naar 108 is geen duwtje. Dat is een herpositionering die de markt inhaalde.

Het hotel staat al in de verkoop. Het eerste hoofdstuk is, zoals Emmanuel het zegt, met succes geschreven, en Schroders verkoopt nu met de waarde bewezen in plaats van beloofd.

"Dit is zo'n succesvol verhaal dat we het hotel op dit moment al verkopen, omdat het eerste hoofdstuk met succes is geschreven."

Wat je in die zin makkelijk mist, is de tijdlijn. Eind 2021 tot begin 2026 is amper vijf jaar voor een volledige herpositionering, een wisseling van exploitatiemodel, een renovatieprogramma van 8 miljoen euro en een voorbereide exit.

Barcelona is een leisurestad. Het hotel was ingericht op zakenreizigers.

Toen het team het asset voor het eerst doorliep, was de puzzel meteen duidelijk. Het hotel zat aan de onderkant van vijf sterren, of aan de bovenkant van vier, en leunde richting zakelijke vraag. De kamers hadden grote bureaus. De kleuren waren hard en donker. Het hele product voelde gebouwd voor een segment dat het niet ging vullen.

Barcelona is geen zakenstad zoals Frankfurt of Zürich dat zijn. Het zwaartepunt ligt bij leisure, en dat is ook het segment waarmee je de ADR omhoog kunt duwen. Een centraal gelegen hotel in de gotische wijk richtte zich commercieel gezien op de verkeerde gast.

De andere verrassing was het gebouw zelf. Dario liep er voor het eerst binnen en trof een pand aan dat in het echt mooier was dan op zijn eigen marketingfoto's. Dat is ongebruikelijk. De meeste hotels verkopen zichzelf online te mooi. Dit hotel verkocht zichzelf stilletjes te bescheiden.

Het plan volgde uit die twee observaties. De kamers warmer en meer op leisure gericht opnieuw inrichten. Het F&B-aanbod herzien, met één restaurant volledig opnieuw gebouwd. De algemene ruimtes licht aanpakken. De marketing herpositioneren richting een lifestyle-hotel met plezier, waar een leisuregast daadwerkelijk voor kiest.

Het businessplan moest tijdens de acquisitie ook nog worden bijgesteld, omdat de marktomstandigheden verschoven en verkopers hogere waarden vroegen. Het team schreef de scope of work snel opnieuw in plaats van vast te houden aan een verouderd plan, en Dario is duidelijk dat die vroege bereidheid om de scope te veranderen een van de beslissingen was die de rest van het project mogelijk maakten.

Waarom ze bewust geen internationaal merk aan het hotel hingen

De voor de hand liggende zet voor een hotel van dit kaliber in het centrum van Barcelona was een langlopend management- of franchisecontract met een bekend internationaal merk. Er was, niet verrassend, ruim belangstelling.

Schroders koos ervoor dat niet te doen. De redenering stond vanaf het begin in de investeringsthese. Ze waren niet van plan het asset dertig jaar te houden. Een deel van de waarde zou tijdens hun houdperiode worden gerealiseerd, en een betekenisvol deel zou op tafel blijven liggen voor de volgende eigenaar.

Een langlopend merkcontract beperkt wat de volgende eigenaar kan doen. Het legt fees, standaarden en vaak ook een exploitant vast. Door de exploitatie in eigen hand te houden en het hotel onder zijn eigen naam te draaien, hield Schroders de optie van een rebranding levend als waardedrijver voor de koper.

Die optie is niet theoretisch. Een koper die het hotel geloofwaardig kan omzetten naar een van meerdere internationale merken, of onafhankelijk kan houden, rekent het asset anders door dan een koper die een contract van twintig jaar erft dat hij niet kan openbreken.

"We wilden een deel van de waarde realiseren, en een deel van de resterende waarde zou gedeeld moeten worden met toekomstige eigenaren."

Zo ziet herpositioneren met de exit in gedachten er in een contractenkast uit. Het is geen slogan op een slide. Het is de keuze om níet de deal te tekenen die het snelst had betaald, omdat die bij de exit meer had gekost dan hij tijdens de houdperiode opleverde.

Het lastigste was alles tegelijk doen

Vraag Dario wat het lastigste aan het plan was en hij noemt geen enkele losse werkstroom. Hij noemt het feit dat ze allemaal parallel liepen.

Je definieert en voert kapitaalwerken uit. Je houdt de operatie draaiend terwijl de bouwers op locatie zijn. Je herpositioneert het merk zonder de marketingmachine van een internationale keten achter je. Je haalt risico uit een asset dat dagelijks wordt gerund door een lokale exploitant die de interne richtlijnen van een wereldwijde groep niet volgt.

Daar bovenop relanceer je F&B-outlets en wissel je sleutelposities. Elk daarvan is op zichzelf een project. Ze tegelijk doen vermenigvuldigt het risico, want als één onderdeel niet aansluit op de andere, breekt de strategie stilletjes in het midden.

Dit is het punt waarop veel herpositioneringen stuklopen. Niet omdat een losse beslissing verkeerd was, maar omdat de volgorde aan het begin werd onderschat, en het team in maand achttien aan het brandjes blussen is in plaats van uitvoeren.

Het team van Schroders ontliep die afloop deels door kapitaaldiscipline en deels door mensen. De juiste general manager, de juiste F&B-leiding en de juiste asset-managementdekking tegelijk op hun plek krijgen is wat de parallelle werkstromen bij elkaar hield.

Mensen en kapitaal zijn wat het getal echt beweegt

Als Dario wordt gevraagd welke hefboom het meest uitmaakte, is hij eerlijk over de verleiding om het asset-managementteam de eer te geven. Het echte antwoord, zegt hij, is kapitaalinzet en mensen, in die volgorde of door elkaar.

Kapitaalinzet is wat de fysieke herpositionering mogelijk maakt. Zonder die 8 miljoen euro zou geen enkele slimme prijsstrategie een zakenhotel met donkere kamers hebben veranderd in een leisurebestemming die de ADR omhoog kan duwen. Het geld moest uitgegeven worden, en het moest aan de juiste dingen worden uitgegeven.

Mensen zijn de andere helft. Dat betekent het personeel op locatie, met name de general manager en de F&B-leiding, en het asset-managementteam daarachter. De afstemming tussen die twee groepen is wat een plan verandert in wekelijkse uitvoering.

Emmanuel voegt een derde factor toe: ritme. Eind 2021 kopen en begin 2026 verkopen is amper vijf jaar voor een project van deze omvang, en dat tempo werkt alleen als het team elk kwartaal de exit in gedachten houdt.

"We hadden de hele tijd de exit in gedachten. We konden snel gaan en precies richten op wat we vanaf dag één wilden raken."

Zodra je het einddoel kwijtraakt, rekt de tijd op en krimpt de waarde. Projecten die afdrijven zijn bijna altijd projecten waar de exit het eerste jaar vaag was.

Vijf jaar is snel voor Schroders, en daar draait deze case om

Houdperiodes hangen sterk af van het kapitaal achter het asset. Schroders werkt met uiteenlopende eigenaren en investeerders, en Emmanuel is duidelijk dat private equity sneller beweegt dan gemiddeld. Sommige assets zijn korter dan drie jaar aangehouden. In één bijzonder geval korter dan drie maanden.

De algemene horizon van Schroders is 5 tot 7 jaar, en flink langer voor grote institutionele investeerders die op zoek zijn naar stabiel inkomen in plaats van een waardecreatiecyclus. Afgezet tegen die basis zit vijf jaar voor Barcelona aan de snelle kant.

Wat de case ongewoon maakt is niet de snelheid op zichzelf. Het is de combinatie van een houdperiode van vijf jaar, een volledige herpositionering, een wisseling van exploitatiemodel en een betekenisvolle stijging van de exitwaarde. Elk daarvan in vijf jaar is normaal. Alle vier bij elkaar niet.

De tijdlijn hield stand omdat het team de exit nooit als aparte fase behandelde. Elke operationele beslissing werd getoetst aan wat een toekomstige koper in de dataroom zou zien. F&B-keuzes, personeelskeuzes, contractkeuzes, de volgorde van de capex, alles.

Dat is de praktische betekenis van de zin waar deze case omheen is gebouwd. Het gaat niet om vroeg verkopen. Het gaat erom dat het operationele plan en het exitplan hetzelfde document zijn.

Wat Dario anders zou doen: de voorkant vertragen

Gevraagd wat hij zou veranderen, wijst Dario niet naar de herpositionering of het exploitatiemodel. Hij wijst naar de technische due diligence.

Hij had meer tijd willen besteden aan het onderzoeken van het asset vóór ondertekening, en meer tijd aan het eerste op orde brengen van de documentatie. Niet omdat het plan verkeerd was, maar omdat een stevigere voorkant later wrijving had bespaard, toen het team al met de eerder beschreven parallelle werkstromen bezig was.

Die onderdelen werden ingekort door de transactiedynamiek. Om hotels in Barcelona werd eind 2021 gevochten, en het acquisitietijdpad werd bepaald door de markt, niet door de koper. In een hete deal accepteer je die afruil. Je neemt genoegen met een dunnere due diligence in ruil voor het winnen van het asset.

Die afruil verdient het om hardop benoemd te worden, want in de meeste evaluaties achteraf is technische due diligence het punt waarvan iedereen stilletjes wenst dat het beter was gedaan. Bijna niemand zegt dat over de herpositioneringsstrategie.

De les is niet om elke acquisitie te vertragen. De les is dat je op het moment van tekenen weet welke delen van de due diligence je bewust hebt ingekort, en dat je de eerste zes maanden van de houdperiode inricht op het dichten van precies die gaten voordat ze in jaar drie uitgroeien tot verrassingen.

Een hotel herpositioneren is niet het moeilijke deel. Een hotel herpositioneren terwijl je bij elke capex-post, elke contractclausule en elke F&B-beslissing de exit in gedachten houdt, dat is het moeilijke deel. Het Grand Hotel Central Barcelona ging in minder dan vijf jaar van RGI 64 naar 108 omdat het team het operationele plan nooit losknipte van het exitplan. Als je volgende acquisitie wordt doorgerekend met een duidelijke houdperiode, is de vraag die op dag één de moeite waard is niet wat dit hotel beter maakt. Het is wat de volgende eigenaar wil betalen om het te erven, en welke van jouw beslissingen in jaar één dat bedrag nu al verlaagt.

60 regels

Klik op een tijdstempel om daar te kijken. De opname is in het Engels.

Transcript

60

A good asset manager understands the number. A great asset manager understands what's behind the number. All right, welcome to Inside Hotel Asset Management. This is a Future of Hospitality podcast. So in this series, we are exploring the world of hotel asset management through real, real case studies, and they're being brought to you by industry leaders. So hotel asset management is all about value, so, and value creation.

So today we're going to talk about the Grand Hotel Central Barcelona in Spain. So we are going to hear from the Schroeder Capital team. So they have implemented a very smart repositioning strategy. And by doing that, they not only set up the hotel for long-term growth, but they also prepared it for the exit or for the sale. So maybe a quick reminder for everyone. So in a

hotel, you would usually see 3 entities. So the owner, who would have like an asset manager, someone who manages the investment, um, the operator, and the brand. Some of these entities can be you know, one and the same company. We'll talk about that later as well. So, um, my name is Luc Boschmans. I work for Red Sea Global based in Riyadh in Saudi Arabia, and today we

will be hearing from Emmanuel Disset and Dario Filipponi from Schroeders. Gentlemen, please introduce yourselves. Emmanuel, would you like to start? Head of Asset Management for Schroders Hotels. I look after a portfolio of 45 hotels in 9 different countries worth €3.6 billion. Fantastic. So Dario, please. Yeah, my name is Dario Filippone. I'm one of the asset managers of Schroders Capital. I I'm in charge of 6 assets located

between Poland and Spain. So yes, I travel a lot and I work with Emmanuel now for quite a long time and we are involved in this specific asset of the Grand Hotel Central in Barcelona. Great. So maybe question for Emmanuel. So Emmanuel, how did you become involved in hotel asset management? How did that happen? Honestly, nobody starts a career saying, I want to be a hotel asset

manager. And I think my path was really accidental. I started in operations as an analyst at the Intercontinental in Berlin in the early '90s. Then I moved into finance as an accountant at the, at the time, Churchill Intercontinental in London. Now it's a Hyatt. And that combination, operations on one side and financial discipline on the other, became really the foundation of my career. From there, I moved

into my first proper asset management role with IHG in the UK, and then I worked for owners of Hilton Hotels. And step by step, I really learned the tricks of understanding both how hotels work on the operation side And what are the key objectives of owners and what do you do to value and to maximize the value of a portfolio? So I suppose I'm the living proof

that there isn't one single path into asset management. You can come from operations, finance, development, revenue management. What matters is learning to connect the hotel operations reality with the owner's financial objectives. Okay, thank you, Emmanuel. What about you, Dario? Well, you know, similar to Emmanuel, really it happens by, by chance. Actually, I, after some initial operational experience, I moved into strategic consultancy, and at that time actually

was post the the great financial crisis of 2008, and I was in Africa and I was consulting for owners around the continent for establishing new hotels. And some asset management assignments started to come because clearly the owners needed to reshuffle or reformulate their strategy after that crisis and implement it. And well, This is how we started. I had the chance to asset manage initially an asset in

Mauritius and then another one in Cape Town. And then little by little I grew, you know, in that sense. And then I was called by Schroders and I started, you know, doing it with Emmanuel. Great, thank you. So I was really fascinated, you know, to, to, to read about what you guys did at the Grand Hotel Central in Barcelona. So, um, yeah, I'm, I'm, I would like

to hear more about it. So Emmanuel, would you like to, you know, explain us a little bit what you guys have done there, why, why you've done that, and then we can go into a little bit more detail with Dario? Sure, sure, I'll give a quick introduction and then Dario who has been looking after these assets since— this asset since 2021, is the specialist of this hotel.

Basically, we're talking about the Grand Hotel Central Barcelona. It's a 146-bedroom hotel located in the Gothic district of Barcelona. It's a beautiful building. It has 3 food and beverage outlets, and we acquired it at the end of 2021. We spent a bit more than €8 million to fully refurbish it, reposition it. We went from a classic hotel management contract to direct operations, and Dario will tell you

much more about that. And we basically grew the RGI from 64 in 2022 to 108 in 2026. Wow. This is such a successful story that we are already selling the hotel at the moment because the first chapter of the story has been successfully written. Great. And maybe just, you know, for, for, you know, if we have listeners who, who, who, you know, don't know that much about

hotel asset management, so RGI is the revenue generation index. That's what we use to compare rooms revenues amongst other hotels, right, to see whether we're doing well. So this is, this is a clear example that there's been, you know, quite a big success. Dario, would you like to give a bit more, you know, details? Yeah, absolutely. Listen, this hotel, it's really a great story in the sense

that when we first looked at it, this hotel was kind of positioned in the entry level of the 5-star, maybe higher 4-star if you can to put it this way, upper scale. And what was kind of surprising for us was the fact that although it is in the very city centre of Barcelona, it seemed to be more focused on business rather than leisure, with these rooms that

had big desks. The colours were kind of stark and dark. And when we looked at it, you know, we saw a hotel that could have much potential to actually increase the share of the leisure clientele, which is the one that allows you to increase also the ADR and the performance of the hotel. And then, you know, when we passed through the acquisition period that has been very

quick because of the transaction dynamic, we got into the real life of this hotel. And, you know, we had some initial issues because we actually, we had to rethink a little bit the business plan because some of the market conditions were changed. You know, the owners were probably asking higher value at that time. And, you know, we have been very quick at reshaping the business plan. And

defined or redefined the scope of work for this hotel. So, very interesting, interesting, we changed the scope of work and, you know, after a few years it was definitely the good decision to take. We have redecorated the rooms, changed completely the F&B offer, one restaurant is completely redone, new. We have soft-touched some of the common area, and, you know, we have repositioned the hotel from a marketing

standpoint towards a more lifestyle, joyful type of hotel, again to cater for this leisure clientele. Okay, yeah, interesting, fascinating. I mean, it's It's kind of, yeah, amazing that, you know, you would find a hotel like this, which in a city with so many tourist attractions and such a, you know, great business mix with a lot of leisure travelers and, you know, finding such a centrally located hotel

but actually equipped for business travelers. That's— Yeah, it was surprising to us actually. The biggest surprise, I think it was the first time that I entered into the hotel and I see that it was much more beautiful in real life than in the pictures, you know, like, you know, sometimes you always see these hotels try to oversell or overpromise through the web. And in this case for

us was kind of the opposite. They say, no, no, but this hotel is so beautiful, it's so great. So we need to, give justice, you know, to this beauty of this building and do something very, very nice. It's good. And then you, you decided not to rebrand in terms of, you know, linking the hotel to an international brand, you know. What was the thinking behind that? Listen,

the, the, the strategy was clear from the beginning that, you know, we were not necessarily there for the next 30 years. Okay, you know, we had a clear strategy with our investors that we wanted to extract some of the value, and a part of the remaining value should have been shared with future owners. Okay, and as a result, we thought that it was best, also thanks to

internal capabilities, basically to operate we create the hotel ourselves so that we could give the flexibility to future owners to decide, you know, which type of brand, you know, potential repositioning, you know, and this flexibility as a value for investors that at the end of the day it's very, very interesting and valuable, and this is why we decided not to use, you know, or to rebrand the

property with an internationally renowned brand. Although we know that there is quite a lot of interest, of course. I can imagine. To manage and brand a hotel in this location in Barcelona. So by taking the decision not to sign a long-term management agreement with, you know, well-known international brand or a franchise agreement, you were actually already thinking about, you know, what, you know, in our graph here

would be then the last phase, so the exit, right? Yes, this is very critical in asset management, Luc. You know, it's important to have a clear investment thesis and timeline for whichever target you want to achieve. The targets can be very different in asset management depending on the capital that is behind the investments and And we as asset managers need to make sure that we deliver on

investors' expectations, you know, and that it was clear for us since the beginning, again, that the timeline and the time horizons was not indefinite. And therefore, you know, we had to study the step by steps to achieve the best results possible for our investors. Okay, and so within the whole plan you came up with and implemented, what was the most difficult part of that whole plan? I

would say that the most difficult part was to manage at the same time all the complexities of this investment, which was like the definition and implementation of the works, its timing, the ongoing operations at the same time, the repositioning without a big brand that of course facilitates, you know, such marketing rebranding, you know, working at the same time in de-risking the asset that was managed by a

local operator and naturally, you know, doesn't abide to the international operator's, let's say, policies. So it was very very critical. Also, for example, we had to relaunch, relaunch F&B, F&B outlets, change of key personnel. So doing all of this at the same time is extremely complex, and you have high risk of things going wrong because if one of these pieces doesn't fit with the rest, then you

really risk undermining the overall strategy. That's a good point. So what do you think, you know, which part of the plan had really the biggest impact? What was the, you know, which was the most defining? Yeah, we love to believe that it's us, but of course, you know, then The reality is that, you know, capital deployment is definitely a key element to be able to achieve and

to extract the value of the asset. Definitely, you know, being able to have the right personnel around, so the personnel on site the people in the asset management team. So this alignment that Emmanuel was commenting in his introduction, it's definitely the key to achieve the results in an orderly and quick manner, I would say. So, you know, it is many things at the same time, but definitely

people and capital are definitely the two things that can can make the magic happen. Yeah, people and capital. Yes, Emmanuel, I may, um, just another point on that. I think what made this project particularly successful is the cadence we went through. When you think that we bought in late '21 and we're selling in early '26, that's barely 5 years. And one of the key success of this

this particular project is that we had all the time the exit in mind. We were able to go fast and to target exactly what would we— what we wanted to target from day one. Hence we are where we are because, you know, we started immediately with that mind spirit, that mind frame into we want to go fast, this is what we want to do, and we're just

going to do it. Sometimes you lose track a little bit if you are not that focused, uh, you know, time goes very, very fast, you lose the end objectives and you waste time. On this particular project, we were very successful at keeping the cadence and all the time having the exit in mind. Is the 5 years, is that like a typical hold period for Schroeder's Capital, or

is it, or Does it depend on— No, we tend to— I mean, it depends. We work with lots of different owners and investors. We do work with private equity. Private equity is even faster than that. We've done sometimes hotels that we kept for less than 3 years. We are— Sorry, sometimes less than 3 months, possibly. We had a case indeed where we kept a hotel for less

than 3 months. But I would say that generally speaking, our, our time horizon is about 5 to 7 years, sometimes much, much longer when we work with big institutions. So 5 years is on the faster side. And what's striking is what we highlighted at the very beginning is the successful story within 5 years is just not an okay story. It's a fantastic story. Yeah, within 5 years.

And that's actually the challenge. Great. Is there anything you say now, you know, oh, maybe this or that we, we could have done differently? Or, you know, looking back at the whole, um, repositioning, uh, strategy you had? Um, listen, uh, probably I, I would have improved, uh, the initial technical due diligence. Probably spending a little bit more time investigating the asset. Probably we could have spent a

little bit more time at the beginning in the consolidation of the documentation. But these things had been driven by the speed of the acquisition that again was very high because of the transaction dynamics that we had at that time. But, uh, beside that, I, I believe that the, the, the story and the, and the asset management initiatives were the right one and at the right time, as

Emmanuel commented. Okay. And so, so how would you then, you know, measure the success of such a strategy? I mean, Emmanuel mentioned, you know, the RGI in the beginning, so the market share, which is a clear indication that we are— that, you know, with your, your hotel, you're, you're gaining market share from the competitors. Is, you know, are there any other indicators you look at? Yeah, absolutely.

I mean, please go ahead. Some details, but for me, and without disclosing any numbers, uh, the difference between how much we bought for and how much we're going to sell for is definitely the biggest success that we have, without going into details. Yeah, no, no, definitely. So I understand, you know, the hotel is currently on the market, so you're preparing the exit, you're already advanced. And so

this is going to be very interesting, of course, for your whole team to see, okay, what is now, you know, how are we going to be able to reap the results of this whole strategy of these, you know, 5 years of working on this project. Absolutely. Yeah, absolutely. Clearly, you know, that is the ultimate, you know, measure of success. This is what our investors and co-investors are

judging us on. But let's say that, you know, in order to achieve that ultimate goal, it's important to set the different, let's say, KPIs. That helps you during, you know, the implementation of the asset management initiative that leads eventually to the increasing value of the asset. So, you know, the most important, it's the net operating income of the hotel, how you make it grow. Okay. And then

you ask about how you make it grow. Then it's basically an increase in revenues driven by the change of the segmentation mix that you have. The increase in prices, increase in volume, the repositioning of the F&B outlets. For example, one of the outlets is now Michelin Guide recommended, which is, you know, quite interesting for a restaurant in a hotel, and this improved the overall experience of the

clients staying in the bedrooms, which eventually leads to higher average rates. You know, another key point for me is how you are able to, let's say, de-risk the asset so that the new buyer has a clear framework, a clear idea of what it remains to do to extract, you know, the value that is still in the property. And that is a key measure of success. So when

you move from a technical or legal due diligence that is, I don't know, many pages long, and then at the end of the process, it's focused on just a few items, that is a key measure of success because you have prepared indeed the asset for the next buyer so that he has an easier life. Got it. Yeah. So no, I can really feel what you guys are

saying, how focused you are on this, preparing the asset for the next buyer, make sure he has still some upside. But in the meantime, that the sale will go in easily as well. So that's, that's, that's good. Yeah, that's, that's the key. Yeah. So no, congratulations. I mean, fantastic. Very nice, very nice case study. Very, very good. Very good job. Um, maybe in general, you know, so

a few, a few more questions before we close. So, um, what do you think, you know, what, what do you think what makes an asset— a good asset manager great? So what will be the difference between a good asset manager and a great one? Well, the, the difference is smaller than people think, but it's actually also bigger than most people think. A good asset manager understands the

number. A great asset manager understands what's behind the number. A good asset manager can read the P&L, challenge a budget, monitor RevPAR, GOP, cash flow, etc. That, that's the technical foundation. That's the minimum you need to to be able to do. But a great asset manager knows that the numbers are always late. Let me explain. Uh, hotels show problems before the spreadsheet. Weak pricing discipline, a GM

spending time on the wrong battles, a CapEx project that's improving the product but not the value. That difference, that's the judgment. A good asset manager will report performance. A great asset management like Dario will convert the performance into decision. What do we change? Who decides? By when? What happens if we do nothing? Etc. And the best asset manager can speak both the languages of the operator, of

the hotel manager, and the capital language of the owner. Yeah, I fully agree. Yeah, Dario, you want to add something? I mean, Manuel has a clear view of what is a great asset manager. If I had to add something, I would say that, you know, a great asset manager is also somebody that is able to absorb, chew, digest all these operational issues that we have been commenting

with Emmanuel and translate it into a language that an investor that sometimes has no information, no knowledge on the industry is able to understand. That is also, you know, a key characteristic for me for an asset manager. You know, many of the investors in the industry, they are not really interested in understanding whether the shrimp shall be served in one way or another, or, you know, whatever

operational issues. And, but at the end of the day, that net operating income comes from that detail. So the ability or the greatness of the asset manager is to really take all these operational, financial, legal compliance issues and to be able to explain in very clear terms to somebody that has nothing to do with this, with this detail, and able to convince them and get them on

board and make them understand that this industry is probably one of the best in the world. Very well said. Very good, Dario. Thank you. So You know, in my role, I'm also in charge of our, you know, training plan for our junior colleagues. And, you know, we have around, you know, 10 people in our team who are really interested in learning more about hotel asset management. And

that's one of the reasons why I do this podcast, because I think it's great content for them. So what would you— are there any recommendations or any— is there any advice you could give to young people who say, you know, I would love to become a hotel asset manager? What would you tell them? I would say that that would be, first of all, a great decision, you

know, for somebody who is willing to become an asset manager. And the nice part is that there is no preset path to become one. I would say that they need to understand how to be street smart and then have a very multidisciplinary approach. So learning the operations, learning the finance, learning the investment side, the brokerage, you know, the broader is your understanding of the industry, possibly the

more successful you are going to be in the role because you will understand the different, let's say, angles of different investors, operators, people in operations, banks involved. So that would be my advice, would be Great idea. Start with whatever you want, move to other, you know, roles, learn as much as possible, and that would be the way you can become a great asset manager. If I may

add, sorry, I think you need also to be very ready to handle uncertainty, being able to change the plans if you understand that something is not going as planned. You must be focused or sometimes obsessed with the value creation. You know, that is the key. Our job is really to create value and, you know, as you said, Luc, there are several ways of creating value and You

know, you as asset manager, you need to understand a little bit of everything to really be able to drive that value creation that, you know, in different assets can come from different things. Great. Yeah, so no, I, I, you know, I like it, you know, you said, you know, be obsessed with value creation and as well, you know, try to learn as much as possible. You know

what I always tell, uh, you know, our younger people as well, you know, be and stay curious, you know, ask questions, you know, if it's not clear, don't worry, ask questions, you know, we all started somewhere. So, so we all learned, we all, you know, started with nothing, so to say. So that's a, that's a very good point. In order to conclude the session, first of all,

many thanks to Emmanuel Desez and Dario Filipponi from Schroeder Capital. I think this was a, you know, a great conversation. I really loved it. And, you know, if you people out there listening or watching this, you know, if you enjoyed this conversation, please follow, like, and subscribe and support the channel for future conversations. There's more coming up. We have, you know, some very interesting industry leaders lined

up as well for this Inside Hotel Asset Management podcast. So thank you very much. Thank you for my two guests, and see you soon.

NIEUWSBRIEF

Blijf op de hoogte

Om de dinsdag sturen we de nieuwste aflevering, het centrale debat daarin en het ene getal dat je moet onthouden. Twee minuten leestijd, geen spam.

Gelezen door 4,200 hospitality-leiders

Unsubscribe in one click, any time.